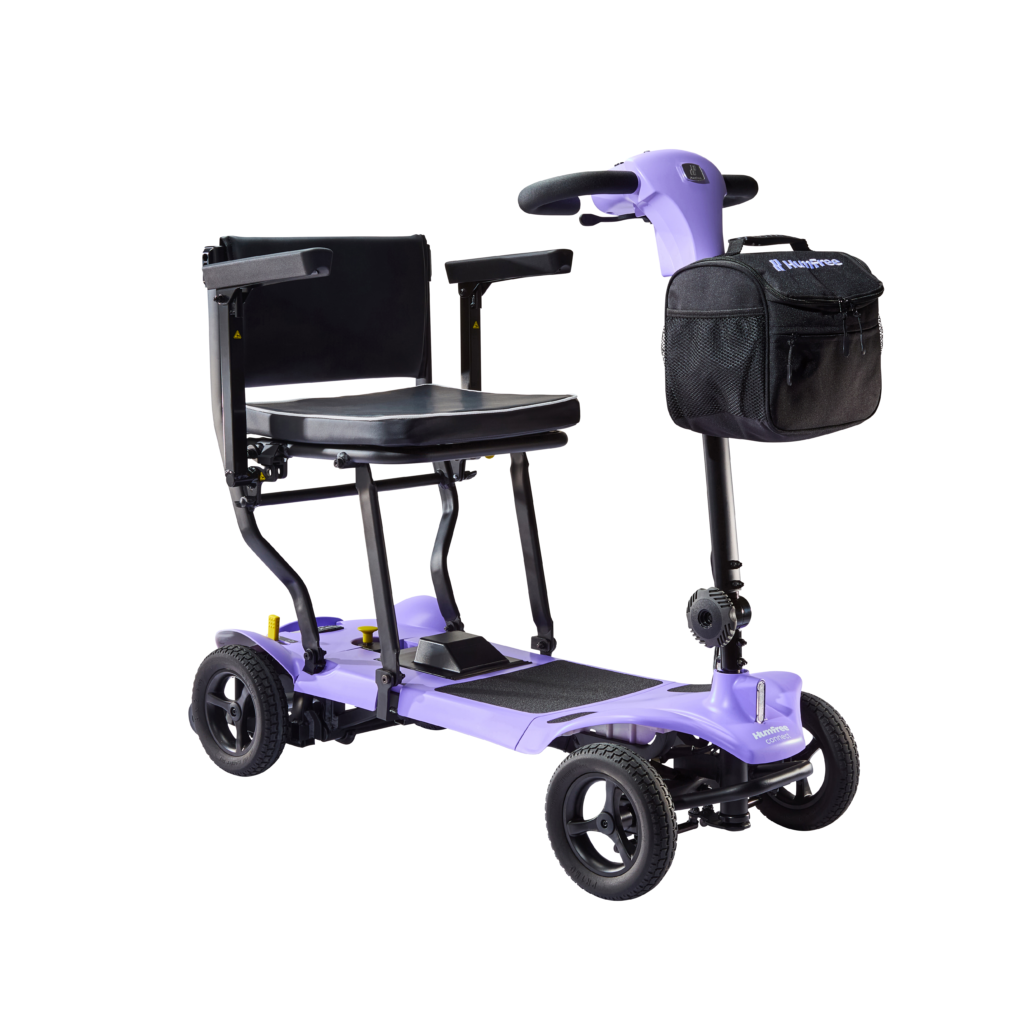
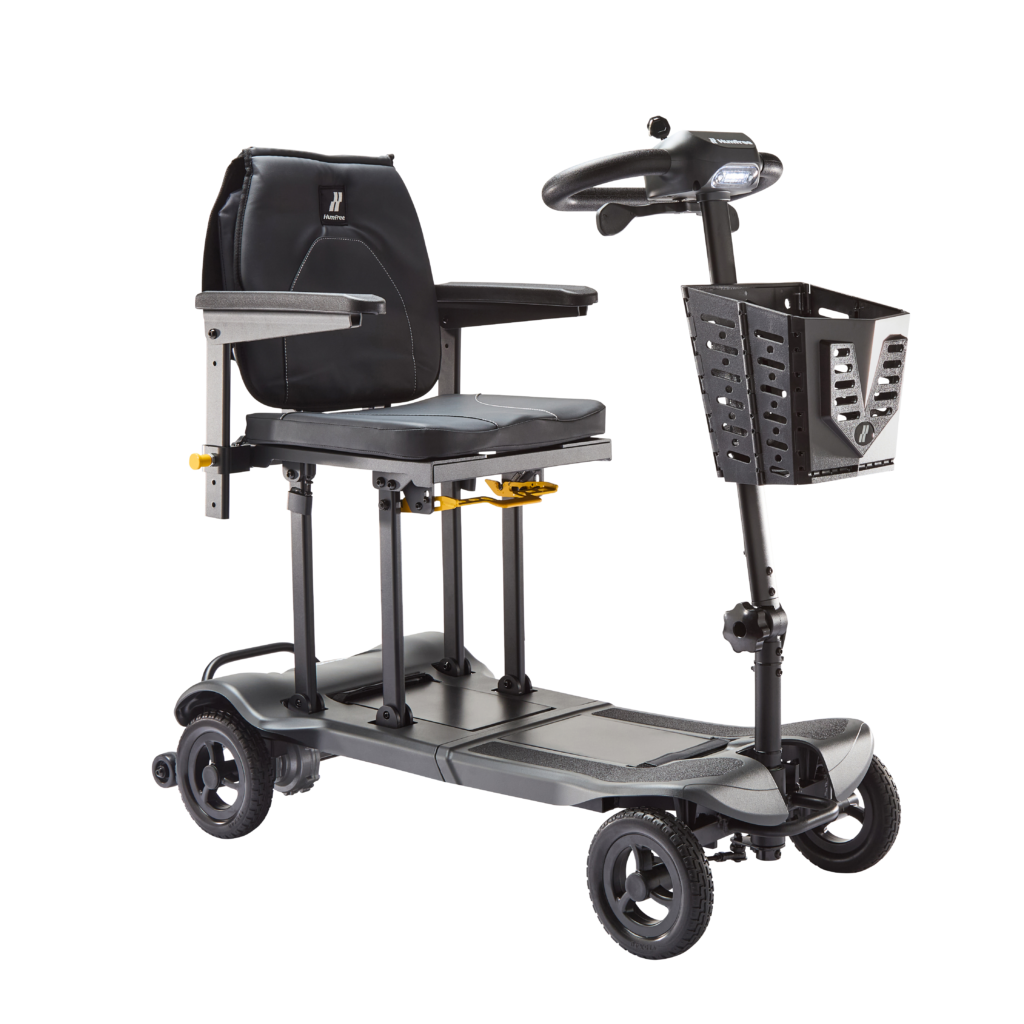
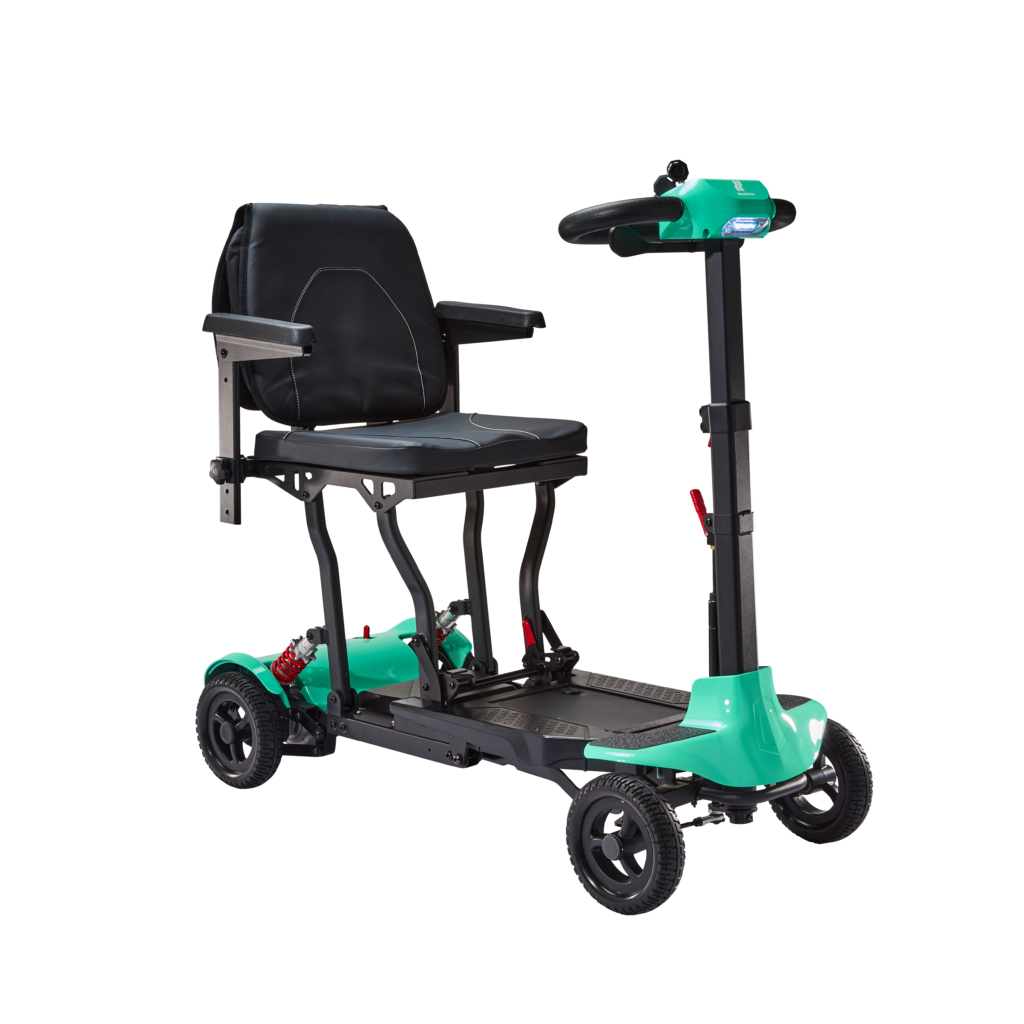
Mobility scooters are more than just a purchase – they give you the freedom to enjoy life the way you want. And that really is priceless.
But in reality, we know mobility scooters are a big investment and, for many people, not something you can simply buy on a whim.
Luckily, there are some options out there, such as mobility scooter finance, that can make owning one a little easier.
So, if you’re wondering what mobility scooter finance involves, how it works, and whether it could be the right choice for you, you’re in the right place.
Key takeaways:
- Monthly payment plans are available for mobility scooters.
- APRs and finance options do vary by provider and your personal financial history.
- Missing finance repayments can harm your credit score and negatively affect your long-term financial health.
Can you pay monthly for a mobility scooter?
Yes, you can!
Everyone should be able to move with confidence – and a monthly payment plan lets you do just that. Splitting the cost of a larger purchase into smaller chunks can make it easier to manage your budget.
How does mobility scooter finance work?
If you’re new to mobility scooter finance, the process may sound complicated. But it’s simpler than you may think.
Instead of paying for your scooter in full, you can spread the cost into more manageable payments each month. Depending on the finance provider and plan you choose, this can be for a period of up to 48 months.
A mobility scooter is a big investment, and if the upfront cost is something you’re struggling with, a finance plan could be something to consider.
What does APR mean?
When you take out finance, you borrow money from a finance provider and repay it over an agreed period.
The APR (Annual Percentage Rate) is the cost of borrowing from your finance provider and is shown as an annual percentage.
These are two types of APR you’ll come across:
Representative APR: This is an advertised interest rate that must be offered to at least 51% of applicants. The remaining 49% may receive a different rate depending on their circumstances.
Personal APR: This works a little differently, as the specific rate isn’t advertised. The rate is based on your personal credit and financial background, so it can vary from person to person.
Note: APR varies massively between different finance providers. Before choosing a finance plan, make sure you calculate whether you can comfortably manage your repayments.
What types of finance options are available?
Just one quick search for ‘mobility scooter finance options’ comes up with hundreds of results. Where to start, what to click, which one to choose… It’s a lot.
That’s why, at Humfree, we’ve made the process less stressful.
We only work with two UK-based lenders to offer simple, flexible payment options:
Propsenio Finance
When buying a Humfree mobility scooter with Propsensio, you could be offered a representative APR of 16.9% with a typical loan term of 48 months. Flexible options are available depending on your financial circumstances.
Snap Finance
Snap Finance works in a similar way – with finance available for up to 48 months at a rate from 29.9% APR.
They also have a ‘Pay in 4’ option. This allows you to pay for your scooter in four manageable chunks over four months. And if you can pay within the four months, your interest may be cancelled.
While you may pay more per month, it could work out to be a cheaper option in the long term.
How much could your monthly payments be?
Your monthly payments will really vary depending on the cost of your scooter, the length of your plan, and the interest rate.
But how does this work in practice?
Here’s a table of what your payments might look like* for a £3,465 scooter, with a £50 deposit and a representative APR of 16.9%.
| Term | Deposit | Monthly Payment | Total Paid* | Finance Charge* |
| 12 months | £50 | £307.70 | £3,742.40 | £327.40 |
| 18 months | £50 | £210.00 | £3,830.00 | £415.00 |
| 24 months | £50 | £161.00 | £3,914.00 | £499.00 |
| 36 months | £50 | £117.20 | £4,269.20 | £854.20 |
| 48 months | £50 | £97.33 | £4,721.84 | £1,256.84 |
*These are estimates based on Propsenio Finance’s plan
Mobility scooter finance eligibility
If you’ve previously been rejected by other lenders, you might think you won’t be eligible for a mobility scooter finance plan.
Our lenders at Humfree, Propsenio Finance and Snap Finance offer plans to people with a low income, bad credit, or no credit at all. That’s exactly why we decided to partner with them, as nothing should stop you from getting the most out of life.
What happens if you miss a mobility scooter payment?
Sometimes things don’t go to plan, and missing a payment can happen.
If you miss a payment, your lender can add a late payment charge to your account and then try to collect the payment again within 1-2 days.
Other consequences of missed payments can include:
- Credit score damage: Missed payments can affect your credit score and can stay on your file for six years.
- Default notice: If you continue to miss your monthly payments, your lender may issue a formal notice. Please don’t ignore this, and if you can, pay as soon as possible.
- Repossession or legal action: This is the worst-case scenario. Multiple missed payments can lead to court proceedings and a CCJ (County Court Judgment) which can make it difficult to access credit, rent, buy a house, or take out a loan in the future.
If you’re struggling with your repayments, please speak to your finance provider to discuss a more manageable payment plan while you get back on your feet.
Alternatively, there are UK-based debt-help organisations that give free, independent advice. Find more information on GOV.UK.
We strongly encourage you not to enter into a mobility scooter finance contract if you realistically can’t afford monthly repayments.
Is mobility scooter finance right for you?
Paying for your mobility scooter with a finance plan all comes down to your individual budget and financial situation. That’s why it’s so important to do your own research and choose a plan that’s right for you.
The good news is that, at Humfree, we’ve partnered with two leading finance providers to help make spreading the cost a little easier. With lower deposits, monthly payments, and flexible payment terms, owning a mobility scooter can become a reality – giving you the freedom to get a little more out of life.